Home Insurance Deductible Explained: How It Affects Premiums and Claim Costs
Kicking off with Home Insurance Deductible Explained: How It Affects Premiums and Claim Costs, this opening paragraph is designed to captivate and engage the readers, setting the tone casual formal language style that unfolds with each word.
Exploring the intricacies of home insurance deductibles sheds light on how they impact premiums and claim costs, providing valuable insights for homeowners looking to understand this crucial aspect of insurance coverage.
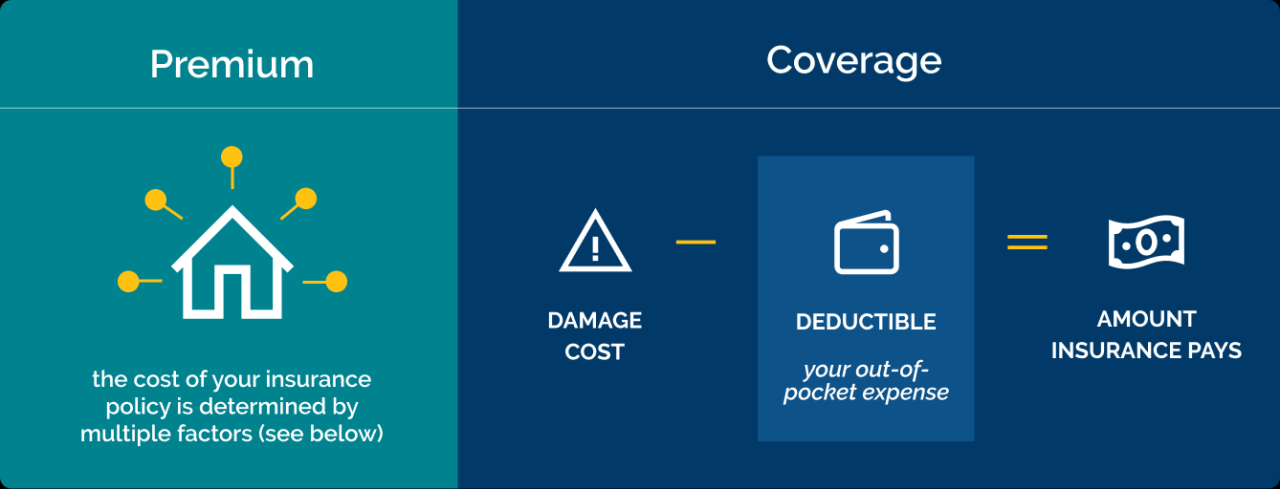
When it comes to home insurance, understanding the concept of a deductible is crucial. A deductible is the amount of money you agree to pay out of pocket before your insurance company steps in to cover the rest in the event of a claim.
The deductible you choose can have a significant impact on the overall cost of your insurance policy. Typically, the higher the deductible you opt for, the lower your premiums will be. This is because you are taking on more financial responsibility upfront, reducing the risk for the insurance company.
When it comes to home insurance deductibles, there are several factors that come into play. These factors can vary depending on individual needs and the location of the home.
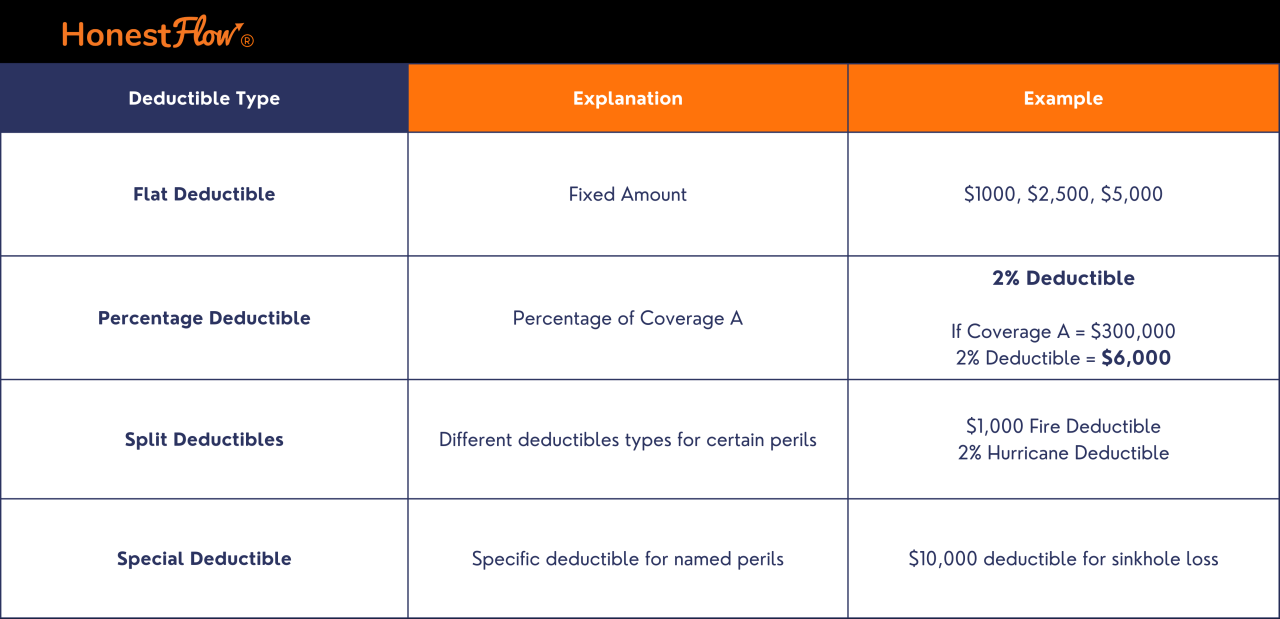
When it comes to home insurance, the deductible amount you choose can have a direct impact on your insurance premiums. The deductible is the amount of money you agree to pay out of pocket before your insurance kicks in to cover a claim.
Understanding how deductibles and premiums are related is crucial in making informed decisions about your home insurance policy.
Choosing a higher deductible typically results in lower insurance premiums. This is because by agreeing to pay a higher amount towards a claim, you are taking on more of the financial risk yourself. As a result, the insurance company may offer you a lower premium to offset the higher deductible.
For example, if you have a $1,000 deductible, you may have a lower premium compared to someone with a $500 deductible for the same coverage.
If you increase your deductible from $500 to $2,000, you might see a significant decrease in your annual premium.
Decreasing your deductible will generally lead to higher premiums because the insurance company will have to cover more of the cost of a claim. On the other hand, increasing your deductible can result in lower premiums but may require you to have more savings set aside to cover the higher deductible in the event of a claim.
If you lower your deductible from $1,000 to $500, your premium is likely to increase.
Conversely, if you raise your deductible from $500 to $1,500, your premium may decrease.
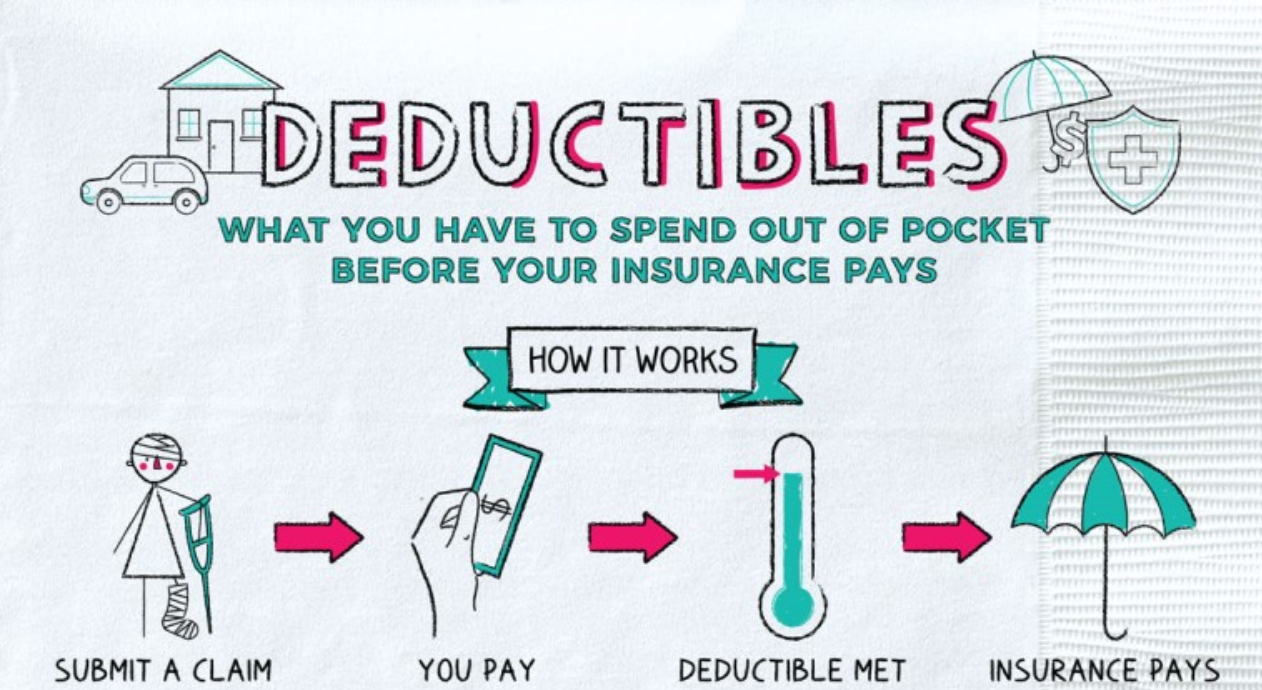
When it comes to home insurance, the deductible amount plays a crucial role in determining the out-of-pocket expenses for claim settlements. Understanding how deductibles impact claim costs is essential for homeowners to make informed decisions about their coverage.
Choosing a higher deductible typically results in lower monthly premiums for your home insurance policy. However, this means that in the event of a claim, you will have to pay more out of pocket before your insurance coverage kicks in.
While higher deductibles can save you money on premiums in the long run, it’s important to consider whether you can afford the higher upfront cost in case of a claim.
For example, let’s say you have a $1,000 deductible on your home insurance policy and experience roof damage that will cost $3,000 to repair. In this scenario, you would need to pay the $1,000 deductible, and your insurance would cover the remaining $2,000.
If you had a higher deductible of $2,000, you would have to pay more out of pocket, but your monthly premiums would likely be lower.
What factors influence the choice of a deductible?
The factors that influence the choice of a deductible include the homeowner’s risk tolerance, financial situation, and the location of the home.
How does the deductible impact insurance premiums?
The deductible amount has an inverse relationship with insurance premiums – higher deductibles result in lower premiums, while lower deductibles lead to higher premiums.
Can deductible choices affect claim settlements?
Yes, deductible choices can impact claim settlements as they determine the out-of-pocket expenses that homeowners need to cover before insurance kicks in.